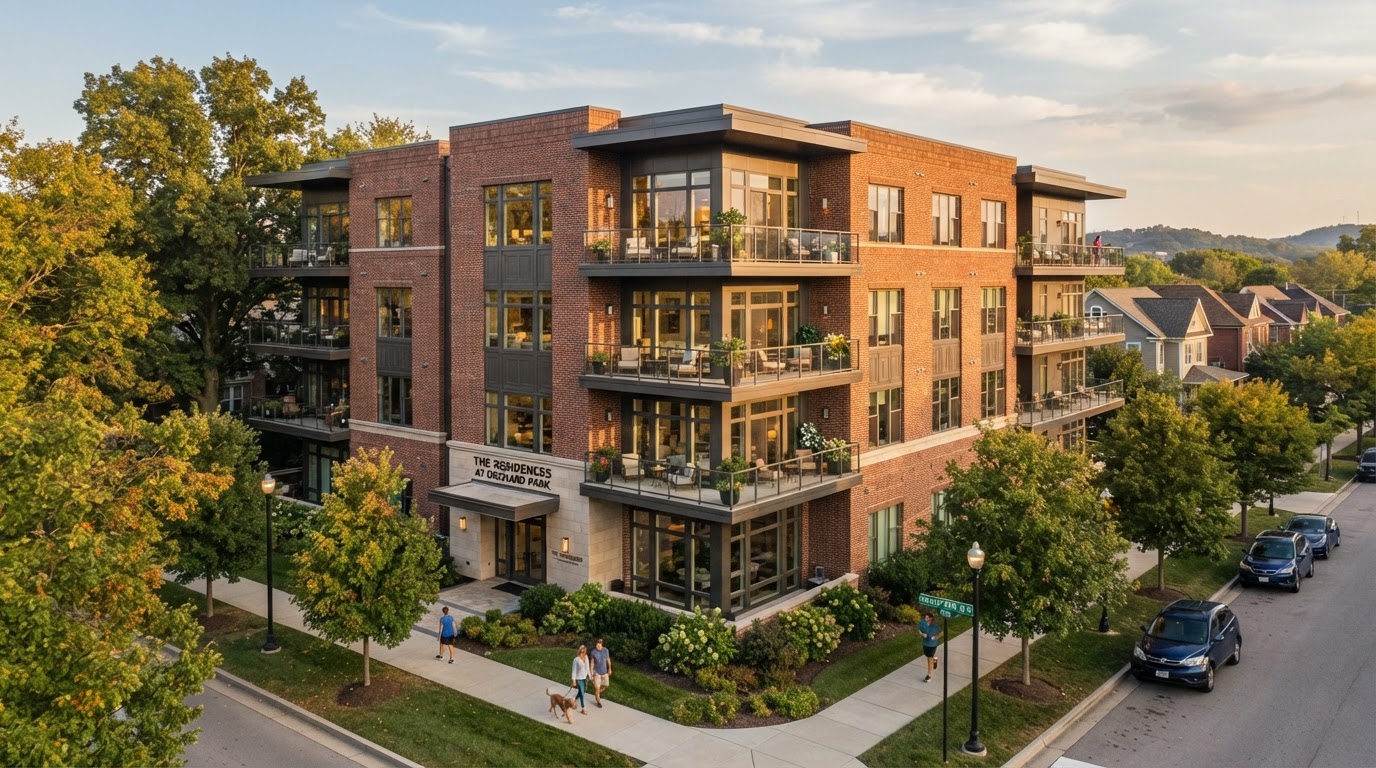
Condominiums offer a lower-maintenance path to homeownership that appeals to many Greater Cincinnati and Northern Kentucky buyers — first-time buyers, downsizers, professionals seeking walkable locations, and anyone who prefers that someone else handle exterior maintenance. But purchasing a condo is fundamentally different from purchasing a detached single-family home, and the difference goes well beyond the unit itself.
Why Condo Living Works for Many Buyers
For many buyers, condominium living provides a lifestyle that single-family homeownership simply cannot match. The reduced responsibility for exterior maintenance — which may include lawn care, snow removal, roof repairs, and building exterior upkeep depending on the community — can free up time and appeal particularly to busy professionals, frequent travelers, and buyers seeking a lock-and-leave lifestyle.
Condominium communities often provide access to shared amenities, such as swimming pools, fitness centers, clubhouses, tennis or pickleball courts, and secure entry systems, that might be cost-prohibitive in a private single-family setting. Additionally, condos frequently offer prime access to walkable urban cores, historic riverfront districts, or vibrant suburban centers across Greater Cincinnati and Northern Kentucky.
Those conveniences come with shared financial and governance responsibilities — which is why understanding the association matters just as much as evaluating the unit itself.
Buying the Unit Means Buying Into the Association
When you buy a condominium, you are not just purchasing your individual unit. You are also purchasing an ownership interest in a shared property — the building, the common elements, and the financial structure that maintains them. The condominium association governs that shared property, and its financial health, rules, and management decisions directly affect your ownership experience and your future resale value.
This is why evaluating a condo requires evaluating the association alongside the unit. A beautiful unit in a poorly managed building can become a frustrating and expensive ownership experience. A modest unit in a well-managed building can provide a very different ownership experience from a unit in an association facing financial or maintenance challenges.
Start With the Monthly Condo Fee — But Don't Stop There
The monthly condominium assessment — often called the condo fee or HOA fee — is one of the first numbers buyers look at, and for good reason. It affects your monthly carrying cost and your purchasing power. But a lower monthly fee is not automatically better.
A fee that is artificially low because the association is underfunding reserves may look attractive today and produce a special assessment tomorrow. A higher fee that includes robust reserves, professional management, and consistent maintenance may actually represent stronger long-term value. The question is not simply "How much is the fee?" but "What does the fee cover, and is it adequate for the building's needs?"
The Association's Financial Health Matters
A condominium association's financial condition is one of the most important factors a buyer should investigate. Key considerations include:
- Reserves: Does the association maintain adequate reserve funds for major repairs and replacements, or is it operating largely on a pay-as-you-go basis?
- Budget adequacy: Does the annual budget realistically cover operating expenses and reserve contributions?
- Deferred maintenance: Are there known building issues that have been postponed?
- Pending projects: Are capital projects planned — roof replacement, elevator modernization, façade repair — and are they funded?
- Delinquencies: Are unit owners paying their assessments on time, or is there a pattern of delinquency that could strain the association's finances?
- Special assessments: Have special assessments been levied recently, or are any currently under discussion?
Ohio law (Ohio Revised Code §5311.081) requires condominium associations to adopt annual budgets that include reserves in an amount adequate to repair and replace major capital items in the normal course of operations without special assessments, unless bylaws limit board rate increases or unit owners vote annually by majority to waive the requirement. Kentucky's Horizontal Property Law requires co-owners to contribute toward a replacement reserve fund but does not specify a minimum percentage. Neither state requires a formal reserve study, though both permit associations to conduct one. State law establishes a framework for reserves, but buyers still need to understand whether the particular association they are considering is actually funding its future responsibly.
Condo Financing Has Another Layer
Condominium financing involves a layer of review that does not exist with detached single-family homes. Even when a buyer qualifies for a mortgage individually, the condominium project itself must also meet the lender's project eligibility standards. If the association's finances, reserves, insurance, or physical condition do not meet those standards, the lender may decline the loan — regardless of the buyer's personal qualifications.
This distinction matters more in 2026 than it has in recent years. Fannie Mae and Freddie Mac implemented significant changes to their condominium project review requirements in 2026, and buyers should understand what changed.
The End of Limited Review (August 3, 2026)
Beginning August 3, 2026, Fannie Mae and Freddie Mac eliminated the Limited Review process for most condominium projects with more than 10 units. Previously, the Limited Review allowed certain loans to bypass a full financial review of the association. Now, many more transactions require a Full Review, meaning the lender will conduct a more comprehensive assessment of the association's finances, reserves, insurance coverage, and building condition before the mortgage can be approved.
The practical implication for buyers is that more condo purchases will involve deeper scrutiny of the association. In some cases, this may produce delays. In others, a project that does not meet the updated standards may result in a loan denial for that specific unit — even though the building is not necessarily unsafe or financially distressed. A denial from one lender also does not automatically mean the unit cannot be purchased; different lenders and loan programs may apply different standards.
Higher Reserve Requirements (January 4, 2027)
A second major change takes effect January 4, 2027. For condominium projects reviewed under the Full Review process, Fannie Mae and Freddie Mac are increasing the minimum reserve funding requirement from 10% to 15% of the annual budgeted assessment income. A project may qualify without meeting the 15% threshold if the association has a reserve study conducted or updated within the last three years that meets required standards and the annual budget funds reserves according to the applicable recommended funding level.
This change does not affect every condo purchase. It applies to conventional loans sold to Fannie Mae and Freddie Mac under the Full Review process. But because those entities back a large share of conventional mortgages, the practical effect is significant: associations that are not funding reserves at the new 15% threshold — or maintaining a compliant, fully funded reserve study — may find that their units become more difficult to finance with conventional loans after January 2027.
Buyers should ask their lender whether the loan program they are using is affected by these changes and should ask the association about its current reserve funding level. If you are considering a condominium in Greater Cincinnati or Northern Kentucky, understanding whether the association is on track to meet these requirements can help you avoid a financing surprise later.
Read the Documents
Condominium purchases involve association documents that do not exist in a single-family transaction. While the specific documents vary by state, project, and transaction, buyers may encounter the declaration, bylaws, rules and regulations, the most recent annual budget, reserve study (if one exists), meeting minutes, and a resale certificate or disclosure package.
These documents are not formalities. They describe the rules under which you will own and use your unit, the financial obligations you are accepting, and the governance structure of the association. Buyers should review them carefully and, where appropriate, consult an attorney. In particular, pay attention to:
- What the monthly assessment covers and what it does not
- Rules regarding pets, leasing, renovations, parking, and use of common areas
- The association's current reserve balance and funding level
- Any pending or anticipated special assessments
- The owner-occupancy ratio, which can affect financing eligibility
- Any pending litigation involving the association
Insurance Works Differently in a Condo
Insurance in a condominium is split between the association and the individual unit owner. The association's master policy generally covers the building structure and common elements. The individual owner's policy — typically called an HO-6 policy — covers the unit's interior, personal property, and personal liability.
The boundary between what the master policy covers and what the individual owner must cover varies by project and by the type of master policy the association carries. Buyers should review the master policy to understand exactly where association coverage ends and individual coverage begins. In some cases, the master policy covers only the building's original construction, meaning any improvements or upgrades made by a prior owner may need to be covered by the individual policy. This is a practical question worth asking before closing.
Rules Can Affect How You Live — and Eventually Sell
Condominium rules are not merely suggestions. They are enforceable conditions of ownership that can affect daily life and future marketability. Common areas where rules matter include:
- Leasing restrictions: Some associations limit or prohibit renting units, which can affect buyers who may need to lease the property in the future.
- Pet policies: Restrictions on pet size, breed, or number are common.
- Renovation approval: Many associations require architectural review before interior or exterior modifications.
- Parking: Assigned spaces, guest parking rules, and vehicle restrictions can affect convenience.
- Use of common areas: Rules governing amenities, noise, and shared spaces shape the living experience.
These rules are not inherently good or bad — but they should align with how you plan to live. A buyer who expects to rent the unit in three years should know the leasing policy before purchasing. A buyer with a large dog should confirm the pet policy. Rules also affect resale: a restrictive leasing policy, for example, may limit the pool of future buyers.
Special Assessments Deserve Special Attention
A special assessment is a one-time charge levied by the association when reserves are insufficient to cover a major expense — typically a capital repair or replacement that was not adequately planned or funded. Special assessments can range from manageable amounts to tens of thousands of dollars per unit.
Buyers should ask whether any special assessments have been recently levied, are currently outstanding, or are under discussion. Meeting minutes can be a valuable source of information here, because boards often discuss major projects before formally assessing owners. A recent reserve study and healthy reserve funding can give buyers more information about how an association is preparing for major future expenses.
Questions Worth Asking Before You Buy
- What does the monthly assessment cover, and has it increased recently?
- What is the association's current reserve balance and funding level?
- Has a reserve study been conducted, and if so, when?
- Are any special assessments currently outstanding or anticipated?
- What is the owner-occupancy ratio, and does it meet current financing requirements?
- What does the master insurance policy cover, and where does individual coverage begin?
- Are there pending or anticipated major capital projects?
- What are the rules regarding leasing, pets, renovations, and parking?
- Are there any pending lawsuits involving the association?
- Does the project currently meet Fannie Mae and Freddie Mac project review standards?
What This Means for Greater Cincinnati & Northern Kentucky Buyers
Condominiums are available throughout the Greater Cincinnati region — from downtown Cincinnati and riverfront Northern Kentucky communities to suburban developments in Hamilton, Butler, Clermont, Warren, Boone, Campbell, and Kenton Counties. The considerations described above apply regardless of location, but the specifics vary by project. Two condo buildings on the same street can have very different financial conditions, rules, and management quality.
The 2026 financing changes make it more important than ever to understand the association's financial condition early in the buying process. If you are relocating to Greater Cincinnati and considering a condo, ask your lender about project review requirements before you fall in love with a unit. If you are already local and simply exploring condo options, the same preparation applies.
Chris's Perspective
A good condo purchase is about more than finding the right unit. The association behind it matters just as much. Its financial health, maintenance planning, insurance, rules, and overall management can affect both your ownership experience and your ability to finance or eventually sell the property.
That's why I encourage condo buyers to evaluate the association alongside the unit itself — ideally before becoming too emotionally invested in a particular property.
If you're considering a condominium purchase, you can explore condominiums for sale across Greater Cincinnati and Northern Kentucky or set up custom home alerts tailored to your search.
Frequently Asked Questions
Sources
Fannie Mae Lender Letter LL-2026-03 and Selling Guide project standards (singlefamily.fanniemae.com). Freddie Mac Bulletin 2026-C (guide.freddiemac.com). Ohio Condominium Property Act, Ohio Revised Code Section 5311.081 (codes.ohio.gov). Kentucky Horizontal Property Law, KRS 381.9167 and KRS 381.870 (apps.legislature.ky.gov). Community Associations Institute reserve study law chart (caionline.org). National Association of Realtors condominium underwriting guideline summary (nar.realtor).